TTDDESTT 348
Climate Study: 36% of Destinations ‘Squeezed’ by 2050
A risk model finds 36% of 2,588 destinations could be “squeezed” by 2050, while beach seasons in Southeast Asia and the Caribbean could contract sharply by 2080.
By Sophie Lindqvist
By 2050, 36% of 2,588 destinations modeled in Destination Climate RiskScan could be “squeezed” under moderate emissions, rising to 62% under high emissions. The study covers 263 countries and territories and finds worsening conditions for sightseeing, swimming, hiking and camping as climate hazards increase.
Travel Forward, an NGO, Risklayer, a risk-modeling firm, and CELTH, the Dutch public-private Centre of Expertise Leisure, Tourism and Hospitality, produced the report. Its percentages describe modeled climate conditions, not observed bookings, arrivals or revenues.
What does “squeezed” mean for travel sellers?
The report calls a destination “squeezed” when it faces more extreme weather and conditions less suited to common tourism activities. The model combines hazard exposure, meaning the climate dangers facing a place, with activity suitability, meaning how well conditions support a particular pursuit.
Each measure sits on a 0–100 index. The authors stress that these scores measure climatic suitability, not forecasts of visitor demand or commercial viability.
Takeaway: “Squeezed” signals less favorable tourism conditions, not an automatic fall in arrivals.
Where could activity conditions deteriorate fastest?\n
Under high emissions, the steepest modeled declines through 2080 sit in the hottest regions:
- Caribbean hiking and camping suitability falls 53 points.
- Southeast Asian swimming suitability falls 48 points.
- Mediterranean hiking and camping suitability falls 48 points.
These are changes in modeled activity scores, not counts of canceled trips or lost hotel nights. Yet they identify where weather-dependent products face the greatest pressure to change their operating calendar.
Takeaway: The largest modeled deterioration sits in hot-region activities and beach seasons.
How will shorter seasons affect revenue and distribution?
The beach-season estimates make the commercial problem more concrete:
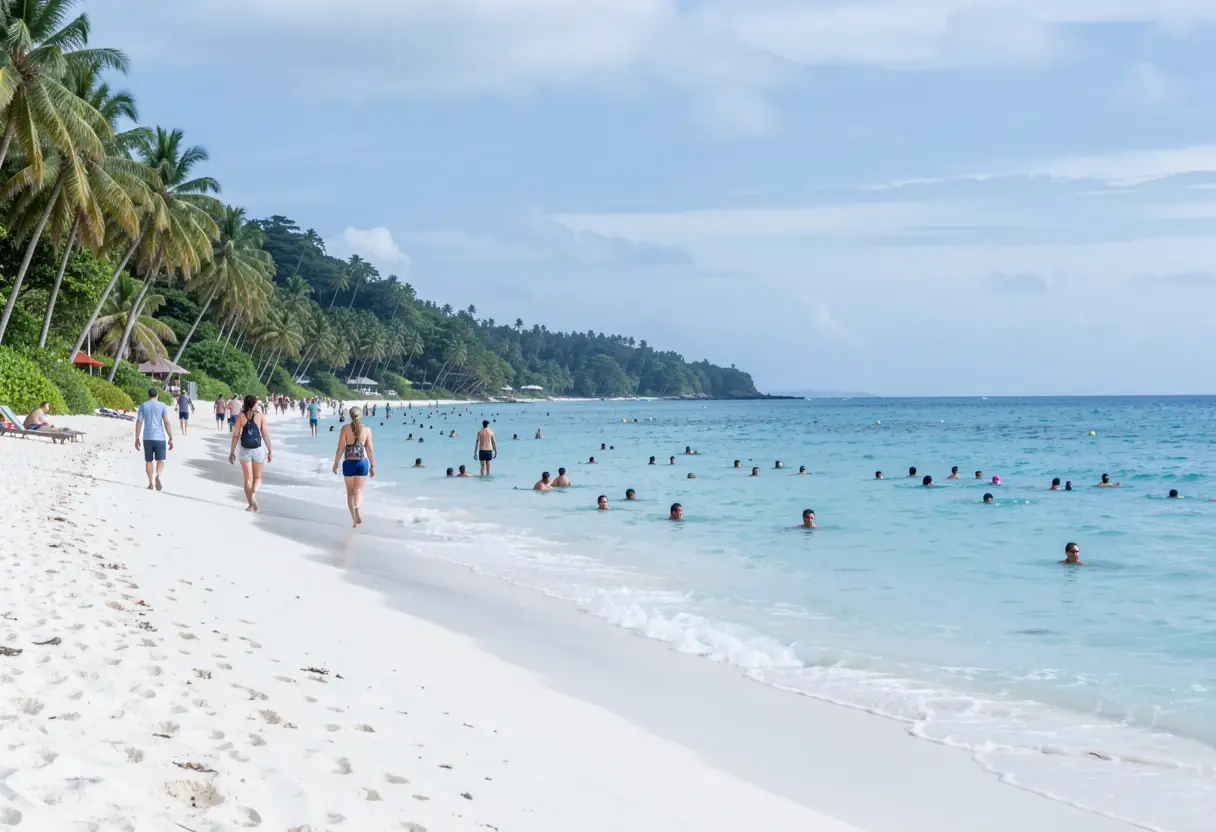
- Southeast Asia’s typical beach and swimming season could shrink from eight months in 2010 to three by 2080.
- The Caribbean’s could contract from 10 months to six over the same period.
For sellers of tours, resort stays and linked packages, a shorter beach season narrows the peak period for weather-dependent products. It also raises questions about discounting, staffing and distribution channels, meaning the routes customers use to book, where intermediaries can charge commissions.
The operational implication is to plan now, not wait for another heat wave. Operators can develop shoulder seasons, the months outside the traditional peak, and cooler-hour itineraries that place activities during the day’s cooler periods.
If customers follow the weather, gross bookings, or the value of sales booked, may shift across the calendar instead of disappearing. That would redistribute revenue among months and channels rather than necessarily destroy it. The study provides no booking, pricing, commission or market-share data to determine which effect sellers face.
Takeaway: Sellers may be rescheduling demand before they lose it.
Where could operators gain from longer activity windows?
Northern Europe and the Nordics are projected to become more comfortable for every activity assessed except skiing. That could support additional hiking, sightseeing and swimming products outside traditional hot-season markets.
The ski assessment excluded artificial snowmaking. It therefore leaves open how much snowmaking could protect ski conditions and sales, rather than providing a clean verdict on the sector’s commercial future.
Takeaway: The north gains activity suitability, while the ski result remains incomplete.
What can sellers conclude, and what can they not?
The report arrives as policymakers meet at COP31 in Antalya, Türkiye, where tourism is a thematic focus. Its results can guide product and destination planning, but they cannot support a claim that 36% of tourism revenue is at risk.
There are no company earnings, market-size or booking baselines against which to validate those commercial effects. Nor does the model show whether affected destinations will gain market share, which channels will retain customers or how commission levels may change.
For sellers, the practical work is to compare the modeled shifts with their own booking pace, customer mix and channel economics. The next commercial test is whether shorter beach seasons and new northern activity windows produce paid bookings, rather than simply relocating existing demand.
via Skift (Source)
More from Sophie Lindqvist
Show full bio
Senior reporter covering people, launches and day-to-day practice in Tourism industry coverage for trade professionals at Travel Trade Desk.
567 articles
Also boarding · Related articles
- HIM16:39
Himalayan Disasters Force Tour Operators to Rework Climate Risk
- SEV15:00
Seven Greek Islands Declare Drought Emergencies. Hotels Are in the Path.
- OFT10:50
77% of Travelers Want Trips That Give Back, Skift Finds
- WTT14:44
WTTC Malta Panel Presses Destinations to Drop the Volume Game
- AMO18:00
A More Dangerous World Is Rewriting Business Travel Rules